If your company buys from, sells to, borrows from or pays fees to a company with the same owner, you have transfer pricing to think about. Under the UAE Corporate Tax Law, those prices must be arm's length: the price independent businesses would agree. Here is what that means in practice, in five short sections.
1. What is a transfer price?
A transfer price is the price one company in a group charges another company in the same group, for goods, services, the use of a brand, or a loan. Because the same owner sits on both sides, nobody bargains hard. The group decides the price, and that decision moves profit between companies, and often between countries.
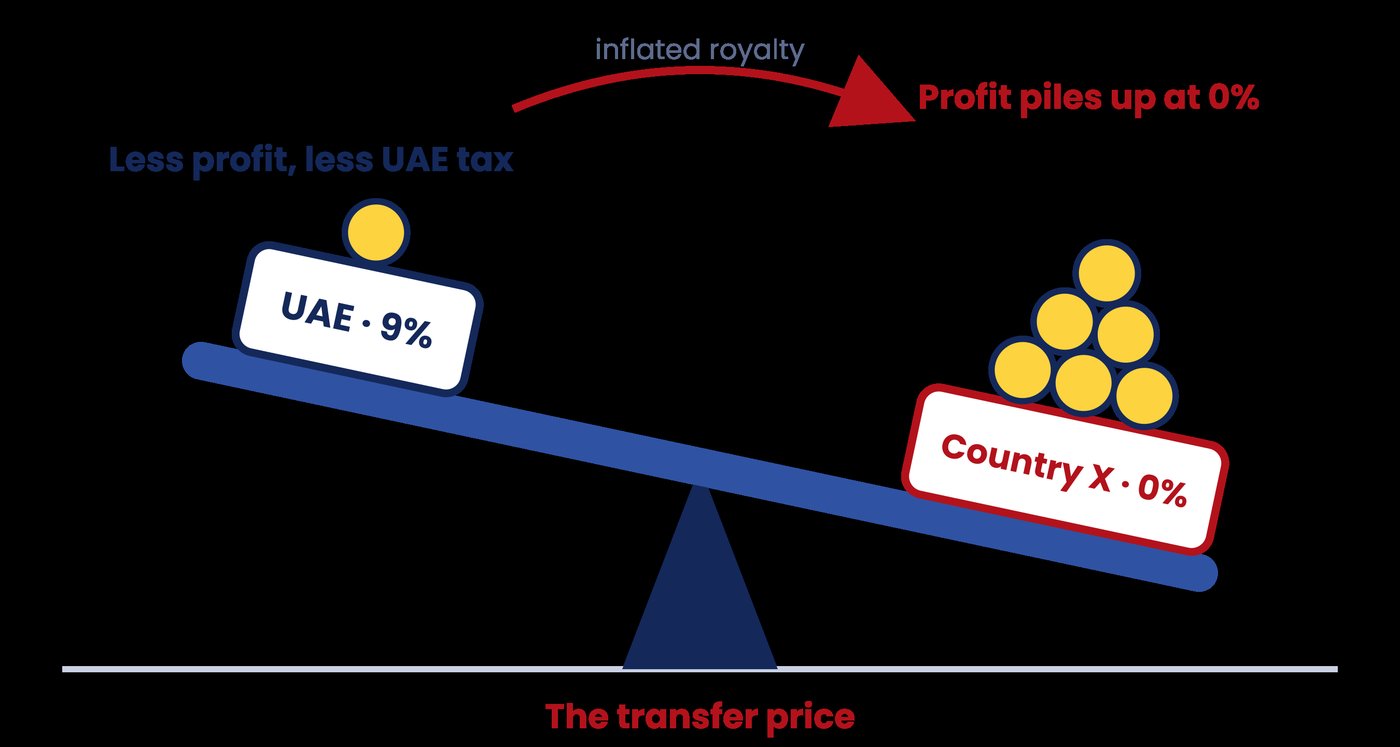
Think of a seesaw. The transfer price is the pivot. Push it one way and profit slides from a company taxed at 9% to a company taxed at 0%. Group profit is unchanged; only the split moves. That is exactly why the FTA reviews it.
2. The arm's length principle (Article 34)
Article 34 of Federal Decree-Law No. 47 of 2022 requires transactions between Related Parties and Connected Persons to be priced as if the parties were independent. The test is simple to say: would strangers have agreed this price? If a mainland factory sells to its sister free zone company at AED 102 a unit, but independent buyers pay AED 110 for the same goods on the same terms, the FTA can adjust the factory's taxable income.
Two practical points:
- Any point inside the arm's length range is acceptable (Art. 34(7)). The FTA accepts the interquartile range.
- Free zone companies: complying with the transfer pricing rules is a condition for Qualifying Free Zone Person status, so getting intra-group prices wrong can cost the 0% rate.
3. Who is "related"? (Articles 35 and 36)
- Related Parties: family members up to the fourth degree; a person and a company they own or control at 50% or more; two companies with a common 50%+ owner, even if they hold no shares in each other; a business and its branch; partners; trustees and beneficiaries.
- Control is wider than shares: half the votes, half the board, half the profits, or significant influence over the business.
- Connected Persons: owners, directors and officers (and their related parties). Payments to them, such as salaries, rent and fees, are deductible only up to market value and only if made for the business.
4. How do you prove a price is arm's length?
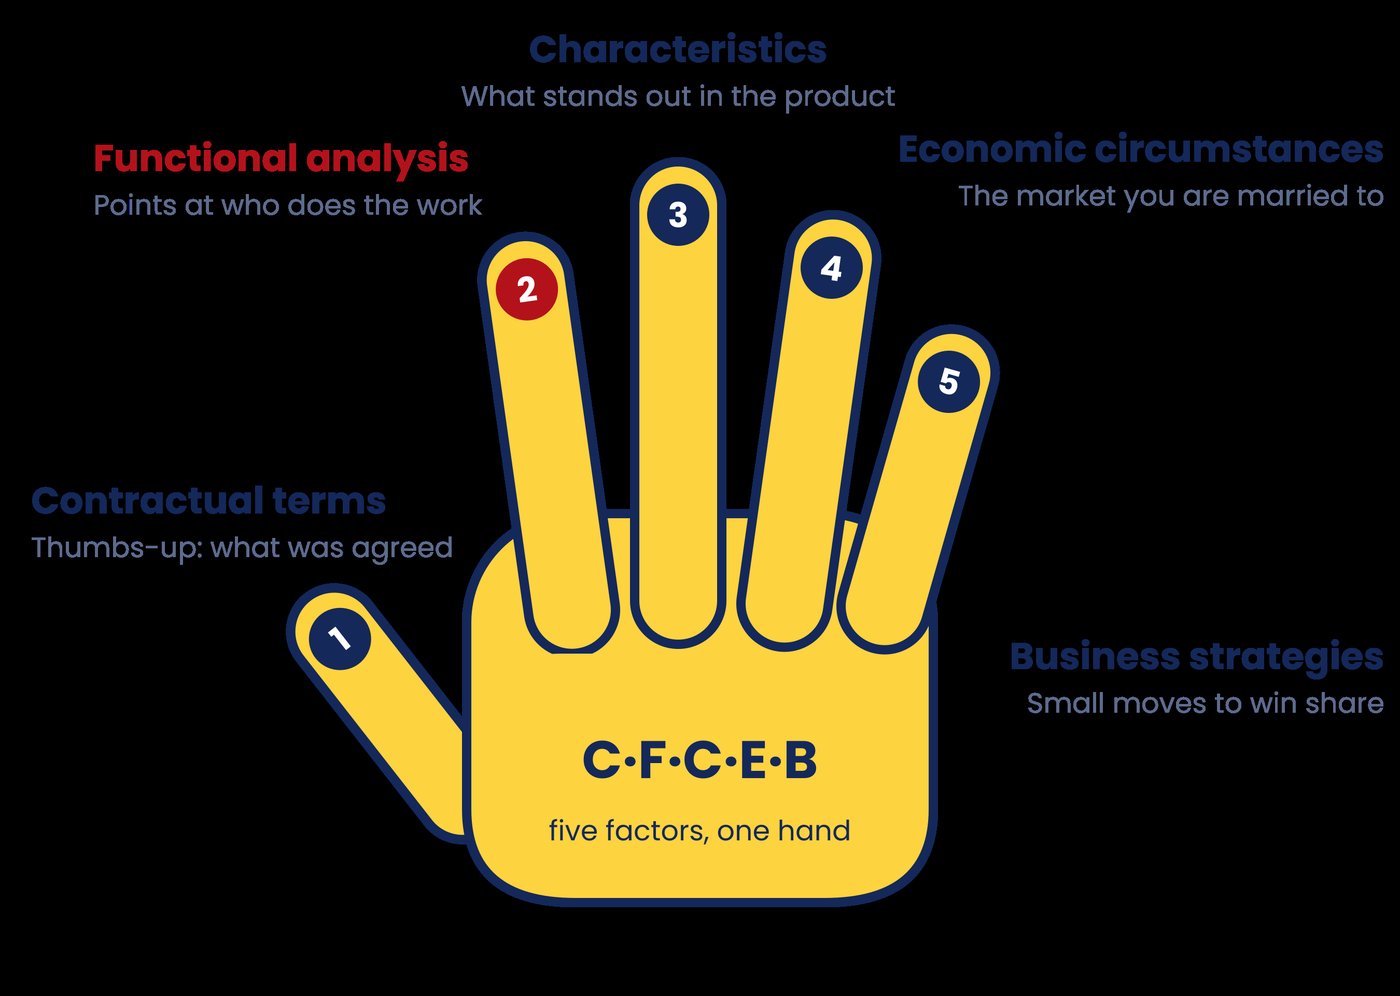
Compare the transaction on five comparability factors. Remember them with one hand:
- Thumb: contractual terms
- Index finger: functional analysis, meaning who does the work, uses the assets and bears the risks (usually decisive)
- Middle finger: characteristics of the product or service
- Ring finger: economic circumstances, the market you are "married" to
- Little finger: business strategies
Then benchmark. The FTA's guide asks you to look for UAE comparables first, then Middle East, then other regions, and to document every search filter.
5. What do you need to file?
| Threshold | What it triggers |
|---|---|
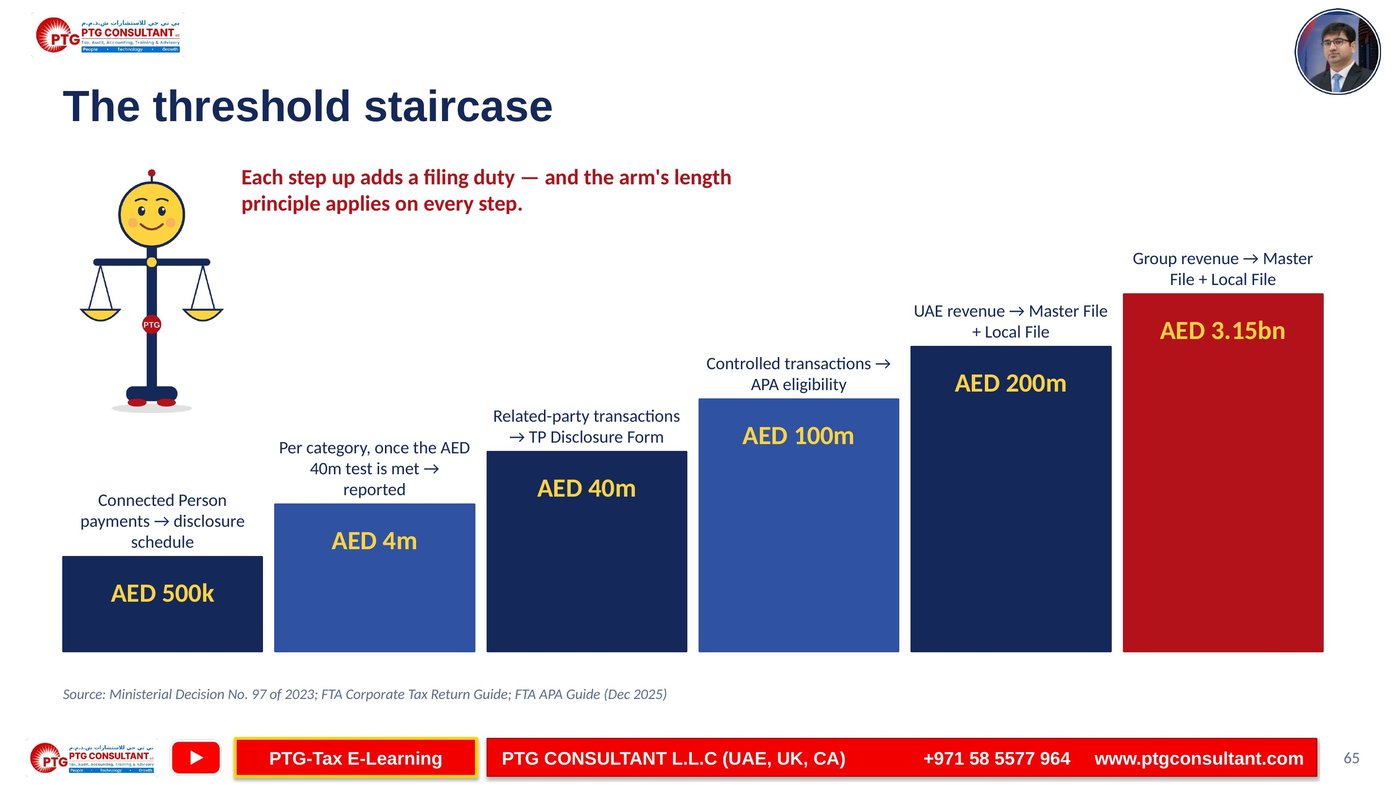
| Payments to a Connected Person above AED 500,000 | Connected Persons schedule in the CT return |
| Related-party transactions above AED 40 million | Transfer Pricing Disclosure Form with the CT return (each category above AED 4m reported) |
| Controlled transactions of AED 100 million+ | Eligible to apply for an Advance Pricing Agreement |
| UAE revenue of AED 200 million+, or group revenue of AED 3.15 billion+ | Master File and Local File |
The CT return and disclosure are due 9 months after the tax period ends. Master and Local Files must reach the FTA within 30 days of a request. Keep records for 7 years. Below every threshold, the arm's length principle still applies.
Learn it properly: free PTG course
We've turned these foundations into PTG's UAE Transfer Pricing Course, Module A: 10 short animated lessons, real global court cases (Apple, Chevron, Cameco, Coca-Cola, Glencore, Amazon), UAE business examples, chapter quizzes and a PTG certificate with a LinkedIn badge when you pass the final exam.
→ Start the free course: UAE Transfer Pricing, Module A
→ Need help with your Disclosure Form, Local File or benchmarking? Book a consultation
Watch the 60-second reels
- The profit seesaw
- Would strangers agree?
- The 50% rule
- Five factors, one hand
- The threshold staircase
- Three auditor questions
Sources: Federal Decree-Law No. 47 of 2022 (Art. 34–36, 55); Ministerial Decision No. 97 of 2023; FTA Transfer Pricing Guide (CTGTP1); FTA Corporate Tax Return Guide; FTA Advance Pricing Agreement Guide (Dec 2025). This article is general information, not tax advice for your specific situation.