What happens after you set a transfer price? A tax authority may change it. It may question whether the deal should exist at all. You can now agree it with the FTA in advance. And every year you must prove it. This guide explains how adjustments, the mutual agreement procedure (MAP), non-recognition, Advance Pricing Agreements (APAs) and documentation work under the UAE Corporate Tax Law, using UAE examples and real court cases.
1. Adjustments: up on one side, down on the other
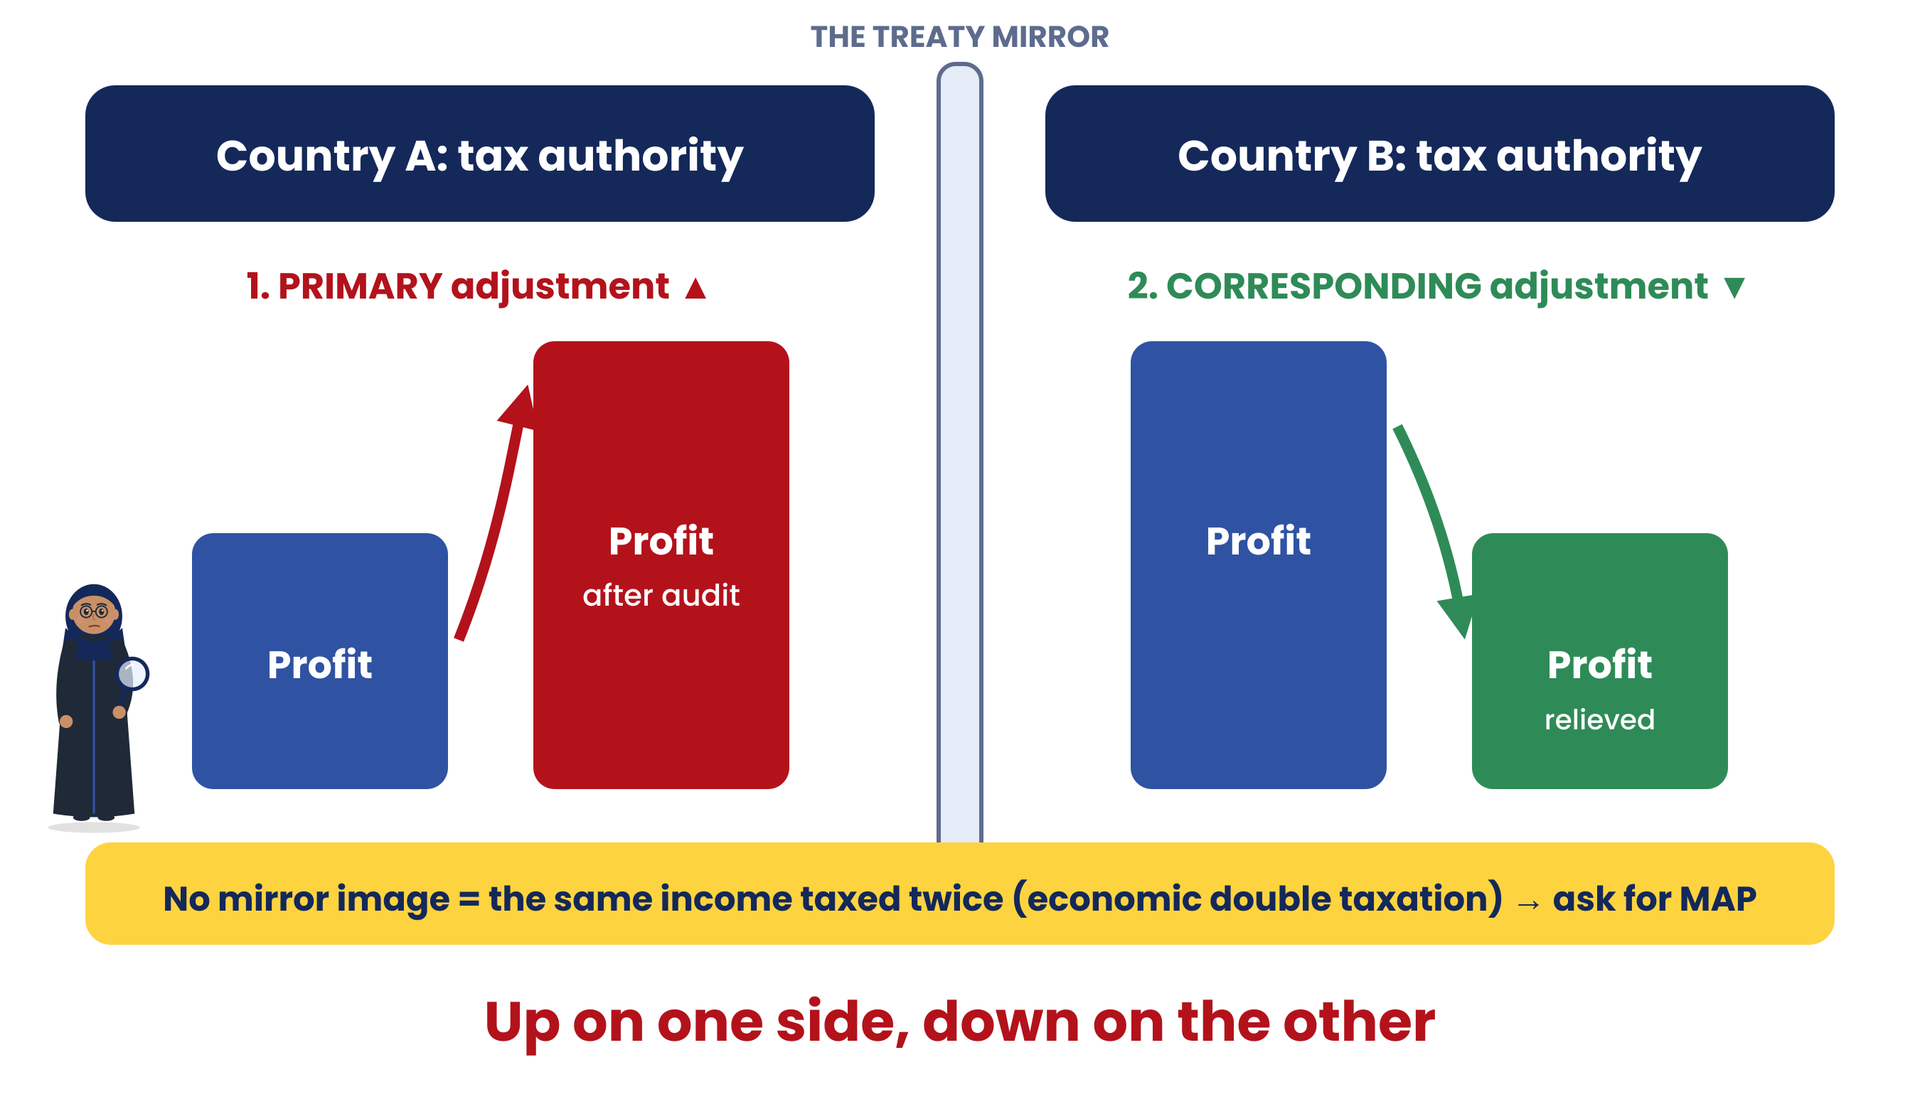
When a tax authority finds a related-party price outside the arm's length range, it makes a primary adjustment, raising one company's taxable profit. Unless the other country lowers the related company's profit by a corresponding adjustment, the same income is taxed twice. Some countries also make a secondary adjustment for the extra cash left behind, treating it as a dividend, a loan or capital. The UAE has no specific secondary-adjustment rule, but your counterparty's country may.
The UAE rule: Article 34(11)
If a foreign tax authority adjusts a transaction with a UAE company, the UAE company can ask the FTA for a corresponding adjustment under the relevant tax treaty. The FTA reviews the foreign position and gives relief where appropriate (FTA Transfer Pricing Guide, s.8.2). For domestic transactions, the FTA reflects its adjustment in the other UAE related party.
| Gulf Spice India → Gulf Spice Trading, Dubai (illustrative) | AED |
|---|---|
| Price charged at cost + 4% (costs AED 50m) | 52,000,000 |
| Indian officer: arm's length is cost + 10% | 55,000,000 |
| Primary adjustment in India | +3,000,000 |
| Corresponding adjustment requested in the UAE | −3,000,000 |
| UAE tax effect at 9% | −270,000 |
Watch the rate gap at home: if the FTA raises a mainland company's profit on sales to a Qualifying Free Zone Person taxed at 0% on that income, the mirror deduction saves nothing.
2. MAP: when two countries disagree
MAP (Article 25 of tax treaties) lets the two competent authorities negotiate a single answer. Under the UAE Ministry of Finance's 2025 guidance:
- the UAE Competent Authority is the Minister of Finance or an authorised representative; requests go to uaemap@mof.gov.ae;
- cases are usually presented within three years of the first notification (check the treaty);
- tax under an FTA assessment is not suspended; agreed reductions are refunded or credited;
- MAP and domestic appeals are not run in parallel; arbitration is available only where the treaty provides it.
3. Non-recognition: rare, and not the same as Article 50
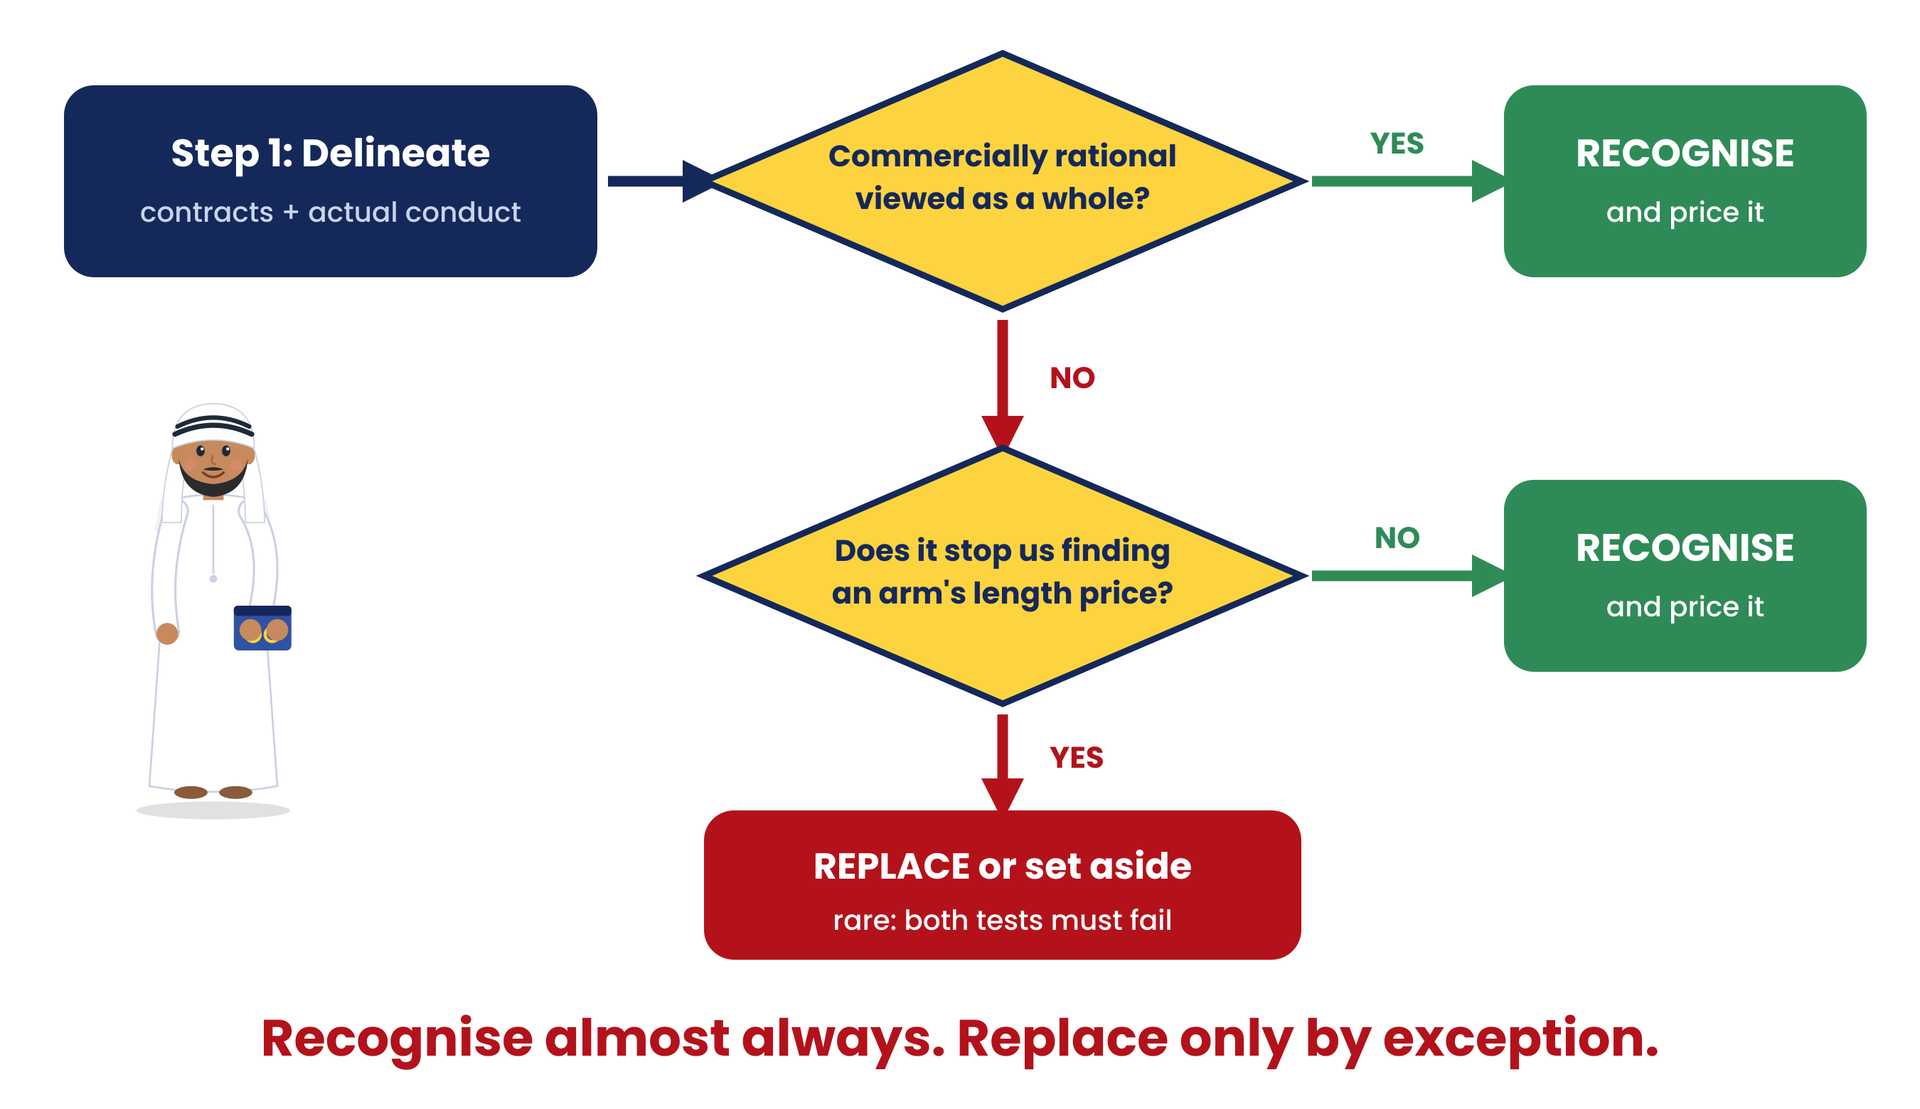
Tax authorities normally accept the accurately delineated transaction and test its price. Under the OECD Guidelines (paras 1.142–1.145), a transaction can be set aside only if, viewed as a whole, it is commercially irrational and that prevents finding any price acceptable to both sides. A real deal at the wrong price is re-priced, not ignored. Separately, Article 50 (the UAE general anti-abuse rule) can counteract arrangements whose main purpose is a tax advantage against the law's intent.
4. UAE APAs: agree your price in advance
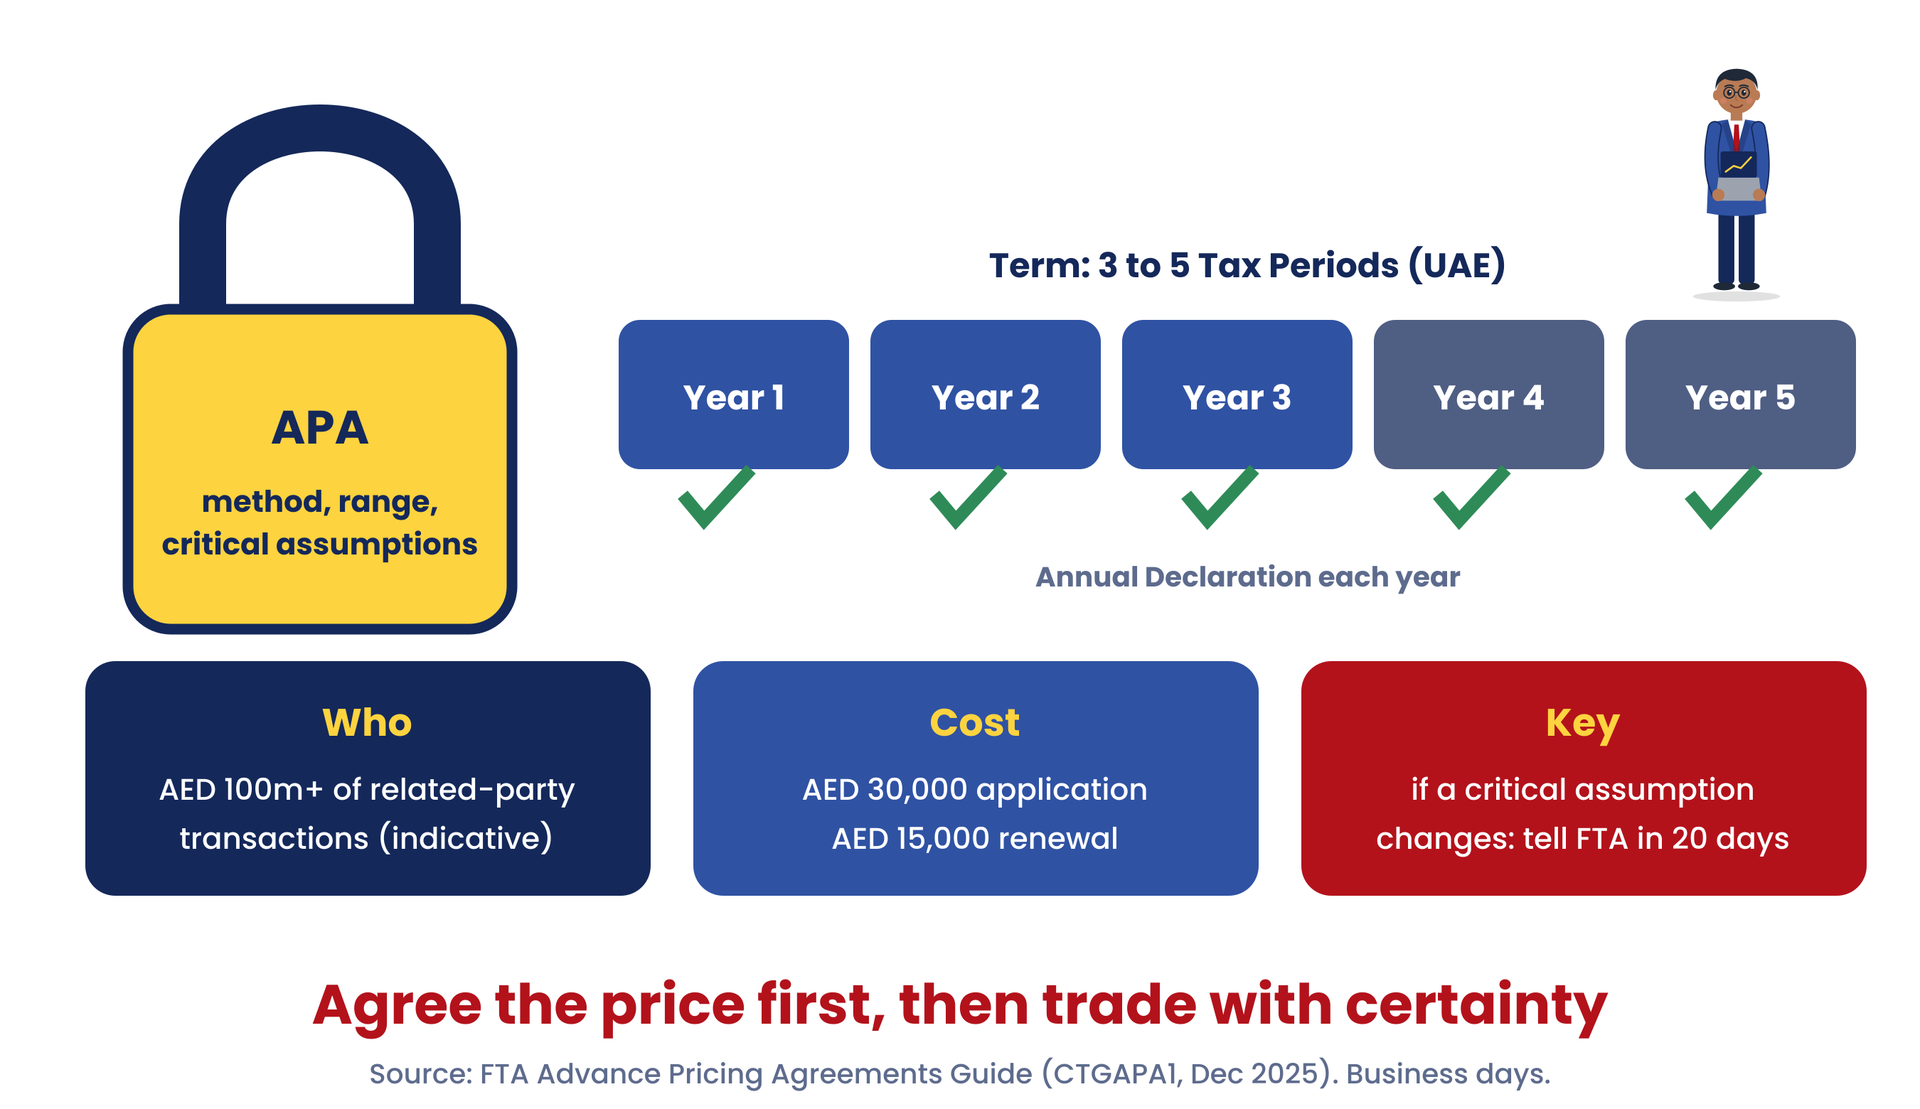
Article 59 and the FTA's Advance Pricing Agreements Guide (CTGAPA1, December 2025) introduced the UAE APA programme:
| Feature | UAE rule |
|---|---|
| Types | Unilateral first (domestic from Dec 2025; cross-border from 2026); bilateral and multilateral later |
| Who | Indicatively AED 100m+ of related-party transactions per Tax Period; real pricing uncertainty |
| Fees | AED 30,000 application; AED 15,000 renewal |
| Term | 3 to 5 Tax Periods, with an Annual Declaration |
| Excluded | Safe-harbour transactions such as low value-adding services at cost + 5% |
5. Compliance: price it, prove it, file it
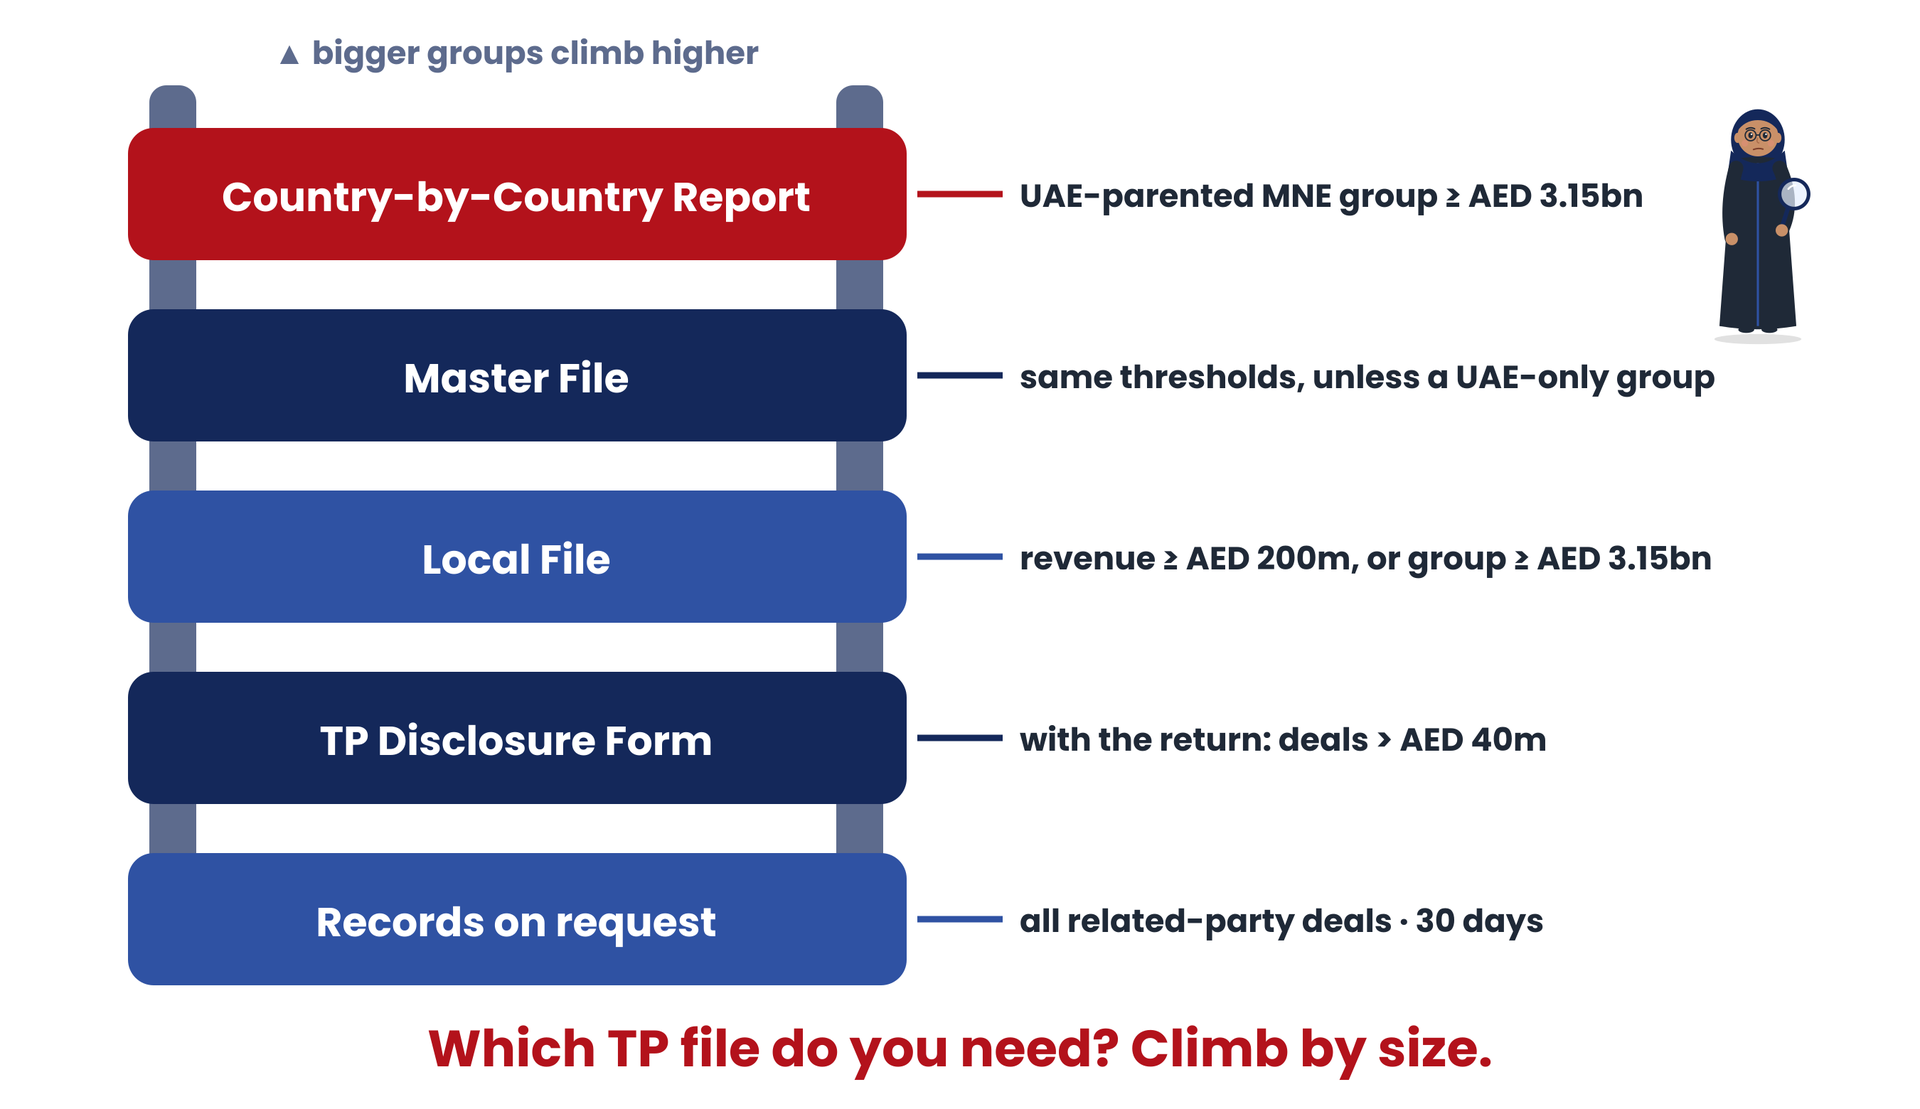
- TP Disclosure Form with the return (within 9 months) when related-party transactions exceed AED 40m; categories above AED 4m are disclosed; a connected persons schedule applies above AED 500,000.
- Local File and Master File at revenue of AED 200m or more, or membership of an MNE group of AED 3.15bn or more (Ministerial Decision No. 97 of 2023); UAE-only groups need no Master File.
- Country-by-Country Report for UAE-parented groups of AED 3.15bn or more (Cabinet Resolution No. 44 of 2020).
- Records produced within 30 days of an FTA request and kept for 7 years; penalties under Cabinet Decision No. 75 of 2023 start at AED 10,000 for missing records.
6. What the courts say
- Vodafone India Services v Union of India (Bombay High Court, 2014): a share issue created no income, so there was nothing to adjust.
- BlackRock HoldCo 5 v HMRC (UK Court of Appeal, 2024): an arm's length loan, but the interest was still denied under an anti-avoidance rule.
- Eaton v Commissioner (US Court of Appeals, Sixth Circuit, 2022): an APA binds both sides; the cancellation was overturned.
- Fiat Chrysler Finance Europe v Commission (EU Court of Justice, 2022): a tax ruling is judged under national rules.
- SNF (Australia) v Commissioner (Full Federal Court, 2011): comparable price evidence beat a "years of losses" argument.
Learn it properly: free PTG course, Module D
Module D completes PTG's UAE Transfer Pricing Course: 10 short lessons with voiceover, a 12-question test after each lesson, six 60-second revision reels and a final exam with a PTG certificate and LinkedIn badge.
→ Start Module D free: adjustments, APAs and TP compliance
→ Earlier modules: A, B and C.
→ Need a Disclosure Form, Local File, MAP or APA support? Book a consultation
Sources: Federal Decree-Law No. 47 of 2022 (Arts. 34, 50, 55, 56, 59); Ministerial Decision No. 97 of 2023; Cabinet Resolution No. 44 of 2020; Cabinet Decision No. 75 of 2023; FTA Transfer Pricing Guide (CTGTP1) s.6, s.8; FTA Advance Pricing Agreements Guide (CTGAPA1, Dec 2025); UAE MoF Mutual Agreement Procedure Guidance (2025); OECD Transfer Pricing Guidelines 2022, https://doi.org/10.1787/0e655865-en; public court records. UAE examples are illustrative. General information, not tax advice.